Keep client work connected
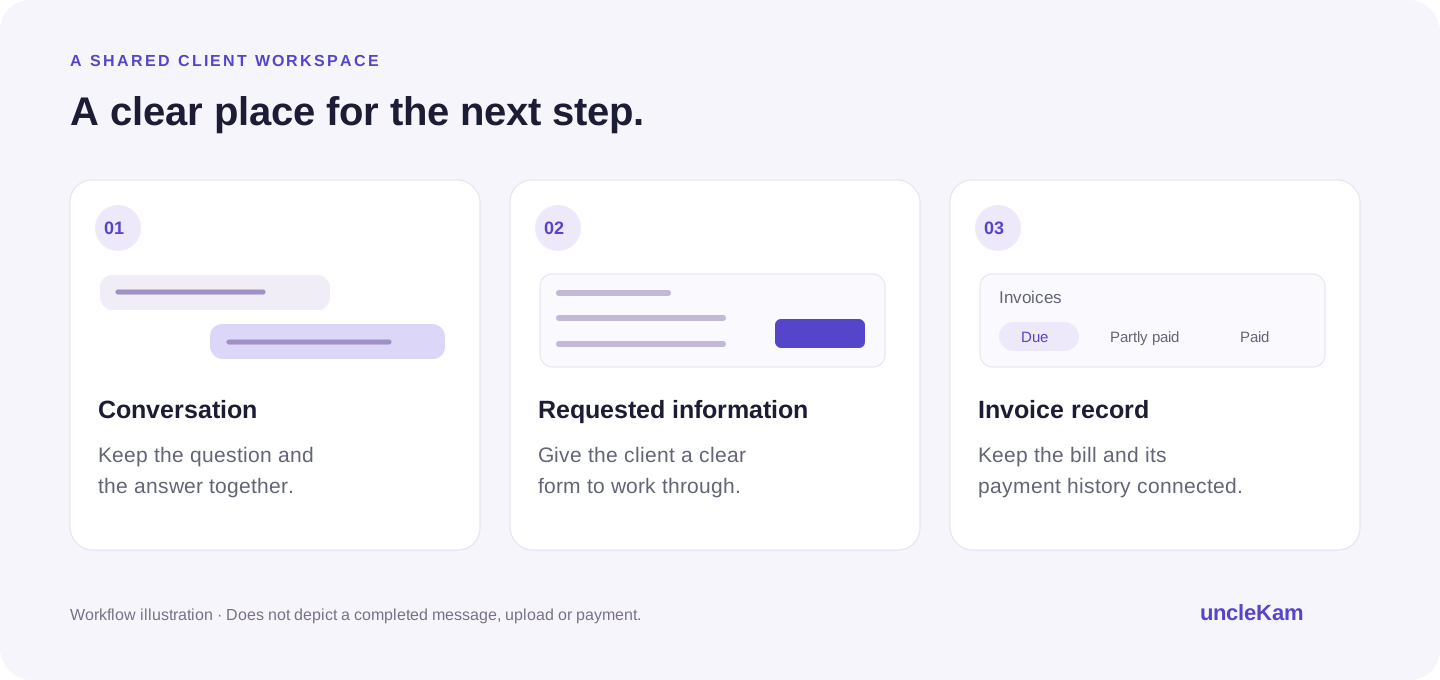
When Uncle Kam connects you with a taxpayer, keep the engagement, client communications, requested documents, invoices and payments on Uncle Kam using the available platform tools. A shared record helps the client follow the work and helps your practice explain what was requested, agreed, delivered and paid.
This policy applies to client relationships supplied by Uncle Kam. The 30% platform fee does not apply to clients you bring independently. If you believe a client was already yours, ask Support to review the source attribution before arranging a different payment route.
Required tax filings, communication with tax authorities and professional obligations still need to be completed through the appropriate channels. Use approved external tools when necessary; keep the relevant engagement record on Uncle Kam and do not use those tools to divert covered payments.
Why Uncle Kam charges 30%
Uncle Kam charges a 30% platform fee on client payments for Uncle Kam-supplied clients. The fee helps fund the work behind the relationship: attracting and connecting taxpayers with professionals, operating the shared workspace and payment workflows, and providing client and Tax Pro support.
- Client acquisition and matching: helping taxpayers find a professional for the work they need.
- A shared workspace: keeping conversations, requested information and work records together.
- Payment and support operations: maintaining payment records and helping investigate account or service issues.
- Ongoing platform development: improving the tools and experience used by clients and professionals.
The fee supports these functions across the platform; it is not a promise of a specific client outcome, tax result, revenue level or reimbursement. Features and allowances depend on your applicable plan and product terms.
Illustration: 30% of a $1,000 fee-eligible client payment is $300. The remaining $700 is before any other applicable charges, adjustments or practice costs. This is fee arithmetic, not a promised net payout.
Opportunity Credit purchases and any separately applicable subscription charges are separate from the 30% platform fee. Review the fee disclosure and your agreement before accepting paid work.
Keep payout fees clear, too
The 30% Uncle Kam platform fee is a sourcing fee for client payments from Uncle Kam–supplied clients. Stripe-related processing, payout, currency or Instant Payout charges—when applicable—are separate from that 30% rule.
Stripe Connect can apply charges differently depending on the payment flow and account configuration. The actual payment, available-balance and payout records are the right place to confirm whether a Stripe-related adjustment applied and which party is charged. Do not promise a client or estimate a Tax Pro payout by subtracting only the 30% fee.
For a specific payout, review the client payment, the platform-fee disclosure, the available balance and the payout record together. Read the payout and Stripe-fee guide →
Make the platform the client’s starting point
- Keep the scope and next step in the client conversation. A clear message reduces uncertainty about what the client needs to do next.
- Use the project’s requested forms and document workflow for the information you need. Ask only for information relevant to the engagement.
- Keep changes to scope, delivery and price in the engagement record. Confirm material decisions in writing.
- Use the platform’s invoice and payment workflow for covered work. Help the client find the correct invoice instead of offering a personal payment link.
These habits give both sides a clearer history. Support can review the platform information it is authorized to access under the applicable terms and privacy practices. Keeping work on-platform does not guarantee payment, a dispute outcome or tax compliance.
What moving work off-platform means
For an Uncle Kam-supplied client, do not request, encourage, arrange or accept payment outside Uncle Kam to bypass the platform or its fees. An intentional request can violate the rule even if the client does not complete the payment.
- Offering a lower price if the client pays you directly by cash, check, transfer or another payment service.
- Sending a personal payment link or an outside invoice for covered work.
- Moving only part of the payment elsewhere, or routing it through a colleague or another business to avoid the fee.
- Asking a client to cancel, mislabel or hide an engagement so the same covered work can continue outside Uncle Kam.
- Moving the client’s communications or documents to an unapproved outside workflow to conceal the relationship or bypass the required platform process.
A taxpayer asking about another payment method is not, by itself, a violation by the Tax Pro. Decline the request, keep the work on-platform and contact Support. A good-faith fee question, credit review, refund request or payment-provider dispute is not circumvention.
If a platform feature is unavailable or the client needs an accommodation, contact Support before changing the workflow. Written approval must identify the permitted exception. An outside call, required filing or authorized professional tool is not automatically evidence that payments were diverted.
Two confirmed violations end platform access
Proposed policy term for staged review. This consequence is not currently live or enforced. It requires agreement, effective-date and operational alignment before release.
First confirmed violation: formal warning
We explain the conduct, the applicable rule and the required correction in writing. You must stop the off-platform arrangement and keep covered work and payments on Uncle Kam. The warning explains that a second confirmed violation will result in permanent removal and the credit consequences below.
Second confirmed violation: permanent removal
A separate confirmed violation after the first written warning results in permanent removal from the platform. Unused purchased Opportunity Credits are forfeited without refund to the extent permitted by applicable law and the agreement governing those credits. Valid fees already earned are not refunded merely because the account is removed.
This is a specific misconduct consequence. It is different from ordinary account closure or a pause, where unused purchased credits remain recorded under the general credit policy.
We review the relevant evidence and give you an opportunity to explain or challenge an error. Multiple messages about the same incident do not automatically count as two violations. A complaint or automated flag alone does not establish a confirmed violation.
Where an immediate safety concern requires it, account activity may be restricted during review. A temporary restriction is not a confirmed strike or an automatic credit forfeiture. If a decision is overturned, the account and credit records must be corrected as appropriate.
What “no refund” covers
Under the second-violation consequence, forfeited unused purchased Opportunity Credits are not available for further purchases or a discretionary cash refund. Valid earned platform fees are not refunded solely because access ends. Applicable law, the agreement governing the purchase and required payment corrections still apply.
This rule does not confiscate client funds or Tax Pro earnings. Payouts, client refunds, disputed transactions and subscription treatment follow their own applicable terms and obligations. A duplicate charge or legally required refund is not automatically denied because an account was removed.
No automatic expiration is being added to purchased credits. Bonus credits remain subject to the separate bonus-credit terms. A valid review request or card-provider dispute does not, on its own, trigger this misconduct exception.
If a client asks to pay outside Uncle Kam
Keep the reply calm and practical. Explain that using the shared workspace keeps the work and payment history together.
Let’s keep the work and payment in Uncle Kam so we both have a clear record of the engagement. I’ll help you find the next step in your account. If something is not working, we can ask Support to help.
For help, email support@unclekam.com with the relevant project or opportunity reference and a short explanation. Do not email full tax returns, SSNs, passwords or card details. Ask for the appropriate secure channel if sensitive evidence is needed.
If you believe an enforcement decision is wrong, reply to the decision notice or contact Support with the case reference and the relevant facts. Account removal does not erase the taxpayer’s rights or the professional’s responsibility to address deadlines and required access to client records.
Common questions
Does the 30% apply to clients I bring myself?
No. The 30% platform fee applies to Uncle Kam-supplied clients. Ask Support to resolve any source-attribution error before changing how a covered engagement is billed.
Can a client ask to pay me directly?
They may ask, but you should decline and keep covered payments on Uncle Kam. A request you decline is not itself a confirmed violation by you.
Do two messages equal two violations?
No. The proposed two-violation process requires separately confirmed incidents, with the second occurring after the first written warning. Each case needs a factual review.
Do I lose credits just because I close my account?
Ordinary closure or a pause does not automatically erase unused purchased credits. The second confirmed off-platform violation is a separate forfeiture exception, subject to the applicable agreement and law.
Can the platform keep money owed to my client or my earned payouts?
This credit-forfeiture rule does not authorize taking client funds or Tax Pro earnings. Those amounts follow their separate payment obligations and applicable terms.
Does this prevent required tax filings or professional software use?
No. Required filings and professional obligations still use the appropriate channels. Use approved external tools when needed, keep the relevant engagement record together and do not divert covered payments.